
Home » Condo Loans » Condotel Loans
Condotel Loans
Condotels: Probably one of the toughest property types to finance for institutions. Neither the banks nor the agencies that govern conventional or government loans won’t touch them. At Andes Mortgage, we finance condotels every single day.
A condo-hotel unit is technically non-warrantable, so it takes a portfolio or Non-QM lender who actually understands them. That’s us — and on the right program, you can use the unit’s rental income to qualify.
We explain in detail how to finance a condominium hotel in this page. Read on.
Andes Mortgage · NMLS #2187991
Licensed in GA, FL, TX, SC, AL
Mortgage pros since 2013
Simple explanation
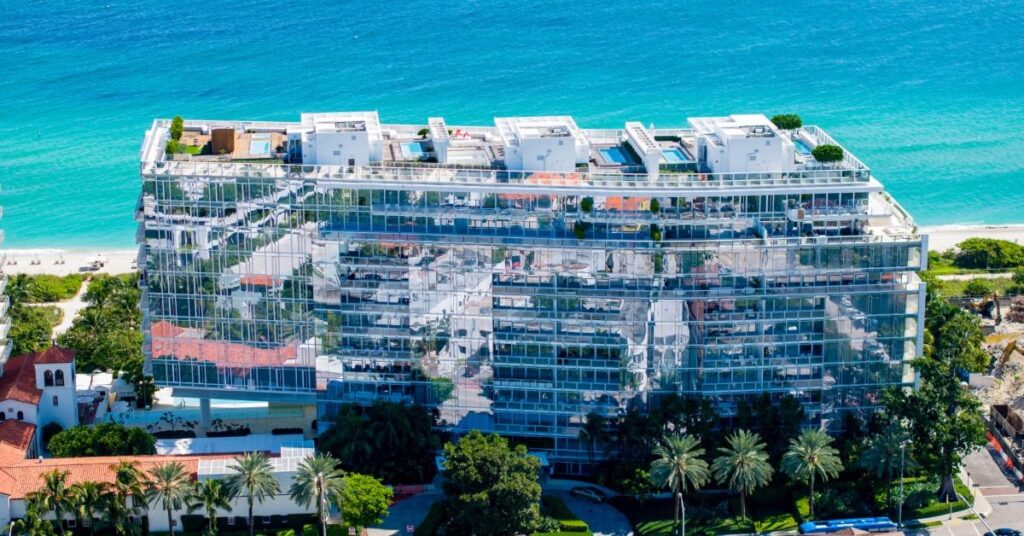
A condotel — condo-hotel or hotel-condo — is an individually owned condo unit inside a building that’s run like a hotel: front desk, housekeeping, a rental program. Some of them are recognized luxury hotel brands like the Ritz-Carlton, The Four Seasons, or St. Regis residences
Because it operates like a hotel, Fannie Mae, Freddie Mac, FHA and VA won’t finance it. That doesn’t mean you can’t buy one. It means you need a specialized condotel loan, which is exactly what we do.
What is a condotel?
A condotel (also called a condo-hotel or hotel-condo) is a resort or hotel property where the individual units are owned as condominiums. Owners get a vacation home they can use, and when they’re not there, the on-site rental program rents it out nightly like a hotel room. Think beachfront towers in Florida, ski-resort units, and downtown high-rises with a hotel flag.
The appeal is obvious: a vacation property that helps pay for itself. The catch is financing. Because the building runs on hotel operations and transient, nightly rentals, it doesn’t fit conventional condo rules — so a condotel is non-warrantable by definition, and it needs a portfolio, Non-QM or DSCR loan instead of a standard mortgage.
Why condotels are hard to finance
Here’s the thing: it’s not about the borrower — it’s about how the building operates.
The agencies won’t buy a loan on a project that functions like a hotel: transient nightly occupancy, a rental-management program, hotel-style services, and often a hotel brand on the door. Those are exactly the features that make a condotel appealing to own — and exactly why conventional, FHA and VA financing is off the table.
So condotel loans live in the specialty world: portfolio and Non-QM programs priced for the extra risk. That means a somewhat higher rate and a larger down payment than a standard condo — but with the trade-off that you can often qualify using the property’s rental income, and close in an LLC.
On our Non-QM portfolio programs, we finance condotels with Full Doc, Bank Statement Loans, Asset Qualifier, P&L loans, Foreign National and DSCR.
What condotel financing looks like
General ranges across our condotel programs. Exact terms are program-dependent and confirmed for your unit and file — this isn’t a commitment to lend.
loan-to-value on a purchase (about 25% down), program-dependent
minimum credit score on eligible programs
loan amounts on higher-end resort units
occupancy; close in an LLC on investment loans
Documentation options include full-doc, bank-statement (for self-employed buyers) and DSCR (for investors). Cash-out refinances are available on eligible units, typically at a lower loan-to-value than purchases.
DSCR
On a DSCR condotel loan, you qualify on the unit’s rental income instead of your personal tax returns — and on eligible programs that includes short-term and nightly rental income. It’s how investors buy resort units without wrapping their personal income into the deal. See how DSCR loans work →
Which condotels we can finance — and which we can't
Condotel programs have their own property and project rules. Here’s what we can touch and what we can’t.
Generally Eligible
- Residential in nature — a real condo unit, not a hotel room
- A full kitchen and a separate sleeping area
- Nightly / short-term rentals and an on-site rental program
- Hotel-style services — front desk, valet, housekeeping
- A recognized resort or hotel brand on eligible programs
- A financially healthy project with adequate insurance
Not Eligible
- Timeshares or fractional ownership
- Units with no kitchen or true hotel rooms
- Mandatory rental pooling on some programs
- Motel conversions
- Projects with major structural or safety issues
- Buildings in serious financial or insurance distress
Requirements vary by program — some allow a hotel brand and rental pooling, others don’t. That’s the value of a broker: we match your specific unit to the lender whose condotel rules it actually fits. More on non-warrantable condo financing →
Different ways to finance a condotel
Qualify on the unit’s rental income – including short term rents on eligible programs. Close in an LLC and keep it off your personal returns.
Buying a resort unit as a second home? Qualify with standard income documents or with bank statements if you are self-employed.
Florida draws buyers from around the world. We finance eligible projects for US non-citizens, including investment purchases.
Answer a few questions and we’ll route you to the Florida condo program that fits your building and income.
Florida is the biggest condotel market in the country
From Miami Beach and Fort Lauderdale to Orlando, Panama City Beach, Destin and the Gulf Coast, thousands of Florida condos operate on a hotel model — and financing them picks up an extra layer of state rules.
On top of everything a normal condotel requires, Florida projects face the state’s post-Surfside requirements: milestone inspections, structural integrity reserve studies (SIRS) and a tight coastal-insurance market. A resort building behind on those can be tough to finance even when the unit cash flows.
Financing a condo in Florida?
Florida is a market of its own — we have a dedicated page for it, covering the state’s biggest condotel markets plus the milestone-inspection and SIRS rules that affect resort buildings: Florida condo loans →
Send us the resort or building and let's see if it qualifies.
Give us the project name and address and we’ll check whether it fits our condotel programs — kitchen, brand, rental setup, project health — then tell you the terms you can expect. Free, no obligation.
Florida’s structural-safety and reserve requirements are established by state law (including Florida Statute 553.899 and Chapter 718) and have been amended several times; deadlines and scope depend on the specific building. The financing paths described reflect the conventional, portfolio and Non-QM condo programs Andes Mortgage brokers through its wholesale lenders, along with current Fannie Mae, Freddie Mac, FHA and VA standards. Loan-to-value limits, credit-score minimums and project requirements are program-dependent and confirmed for your building at the time of quote. This page is educational, not legal advice, and is not a commitment to lend.
Marcos Zambrano
President, Andes Mortgage · MLO NMLS #988935 · Mortgage professional since 2013
Condotel loans FAQ's
What exactly is a condotel?
A condotel is a condo unit inside a building that operates like a hotel — with a front desk, housekeeping and a rental program that rents units out nightly. You own the unit outright as a condo, but the building runs on hotel operations, which is what makes financing different.
Can you get a mortgage on a condotel?
Yes — just not a conventional, FHA or VA loan. Condotels are financed through specialized portfolio and Non-QM programs, including DSCR loans for investors. We broker several of them and match your unit to the one whose rules it fits.
How much down payment do I need for a condotel?
Typically around 25% down on a purchase (up to roughly 75% loan-to-value), though it’s program-dependent and can vary with your credit, occupancy and the project. Cash-out refinances usually require more equity.
Can I use short-term rental income or airbnb income to qualify?
On a DSCR condotel loan, yes — you qualify on the unit’s rental income rather than your personal tax returns, and eligible programs count short-term and nightly rental income. It’s the most popular way investors finance resort units.
Can I buy a condotel through an LLC?
Yes, on investment (DSCR) programs you can typically close in an LLC. Second-home purchases in your personal name are also available on eligible programs.
Is a condotel a good investment?
It can be, in the right resort market — a condotel can throw off strong nightly rental income and give you a vacation property that helps pay for itself. The trade-offs are a higher rate, a larger down payment, HOA and rental-management fees, and a narrower resale buyer pool because the financing is specialized. A good reality check is to run it as a DSCR deal, where the rent has to cover the payment — which is exactly how these loans are underwritten. This is general information, not investment advice.
Do condotels have higher rates?
Somewhat. Because condotels are non-warrantable and priced as specialty loans, the rate and down payment run higher than a standard condo. For many buyers, the rental income the unit generates makes the math work anyway.
Thinking about buying a resort condo? Let's see if it qualifies.
Send us the building and we’ll tell you whether it fits a condotel program — and what your terms would look like.
Andes Mortgage LLC · NMLS #2187991 · Marcos Zambrano MLO NMLS #988935. Licensed for consumer lending in Georgia, Florida, Texas, South Carolina and Alabama. Business-purpose (DSCR) lending available in additional states.
This page is for informational purposes only and is not a commitment to lend, an offer of credit, or a guarantee of any rate, term or program. Loan approval, loan-to-value limits, credit-score minimums, reserve requirements and condo-project eligibility are subject to full underwriting, current lender and agency guidelines, and verification of the specific project. Rates and programs are subject to change without notice. Equal Housing Lender.